
How Much Does Fix and Flip Insurance Cost in Montana?
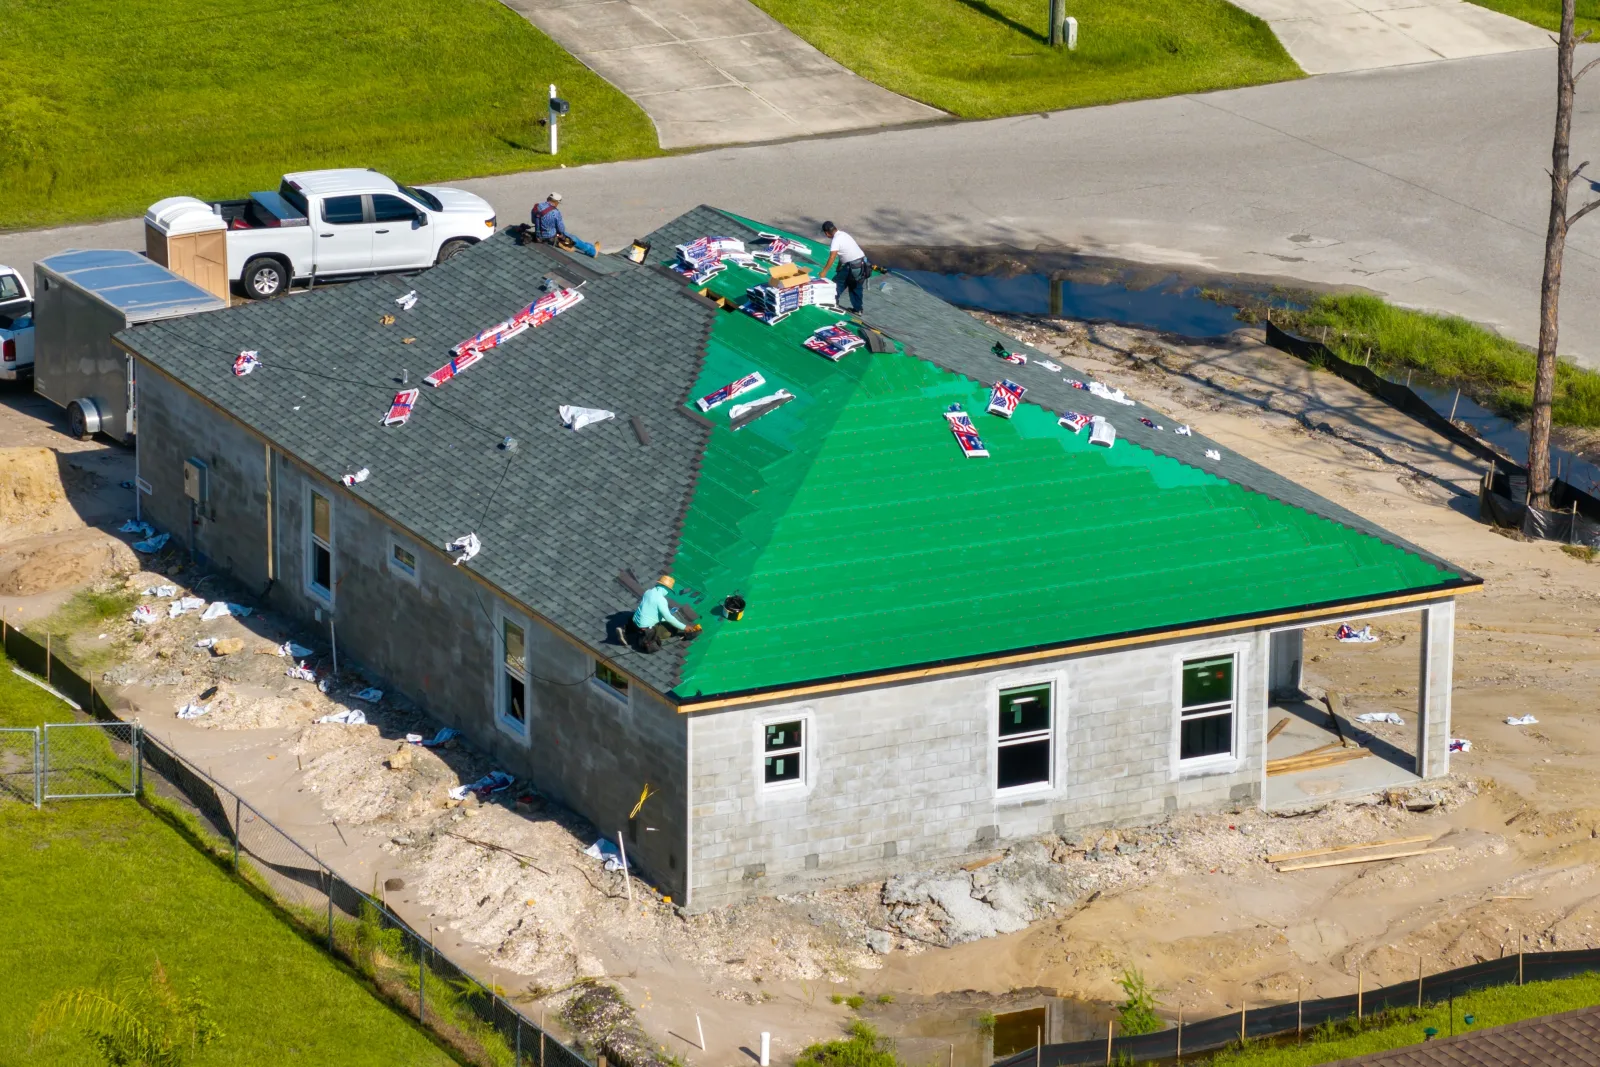
No premium sits on this page for a Montana rehab, and the reason is particular to this state. Two of the inputs a market reads here are still in the owner’s hands while the work is open. The roofing and the siding are one of them. The data sitting behind a wildfire score is the other.
Where the wildfire conversation stops being weather and becomes materials
Montana has legislated around wildfire pricing in a way that lands on a renovation’s shopping list. The Commissioner’s office describes two measures from the same session: a consumer transparency measure requiring insurers that use wildfire risk scores to disclose the underlying data and methodology on request, and a companion measure allowing insurers to offer premium reductions to owners who invest in wildfire mitigation and resilient construction such as ignition-resistant roofs or fire-resistant siding.
The two verbs are not the same verb. One requires a disclosure. The other permits an offer. Neither obliges any market to reduce anything and neither is a building code. Jointly they convert two things an owner would otherwise simply receive — the model behind the number, and the materials the number is partly about — into two things an owner can put an argument to.
It is also why a figure attached to the state name would tell you nothing: the same house, specified two ways, arrives as two different files. The national version of this question opens on which policy form the job lands on. Here that question waits, because two decisions made with a supplier get settled ahead of it.
A score an owner can ask to see, and a spend a market may reward
The disclosure measure is a right of inquiry, not a ruling that any score is wrong. What it hands over is a route to what the score was assembled from. Part of that will be terrain, and terrain does not negotiate. The rest describes the building — and for a few months during a rehab, the building is a jobsite whose exterior has not been ordered yet.
That is the half with a clock on it. Cladding priced off a drawing and cladding already nailed up are not the same conversation with a market, and the second one is much shorter. The useful sequence therefore runs specify, place, install, rather than install and then discover what the specification might have been worth. A builders risk policy bought over an exterior scope is covering the very products the second measure was written about, which is an unusually short line between a purchase order and a premium. Agents placing renovation risk every week start at the scope, and in this state the scope has an argument folded into it.
The order this state puts a renovation file in
Position is the whole of what this column claims, and the top of it is unusual, because the top of it is a shopping list. Montana lets an owner ask how a wildfire score was built and lets a market offer something back for ignition-resistant roofing and fire-resistant siding, so the exterior specification becomes an argument before it becomes a cost. Beneath that sits the permit question, which resolves to whether a certified local program covers the address or the state bureau does. Then the peril this market is being repriced around, then a contractor credential that checks paperwork rather than skill, then the trade boards the state runs and the one it does not. The three at the foot are the rows the schedule and the budget still move, and in this state the first of them is moved by the same exterior specification standing at the top.
- A score you can ask to see, and materials a market may reward One measure opens the wildfire scoring data on request; the other lets an insurer price resilient work back.
- Certified counters, the state route, and what sits outside both Whether a certified local program covers the address decides which office issues the permit and sets the queue.
- Wildfire on the renewal notice, and flood bought separately Fire sits in the form beside hail, wind, explosion and theft; flood is a purchase of its own.
- The credential a bill renamed, and the application behind it Registration became a license, and the application asks for a fee and coverages rather than an examination.
- Wire and pipe answer to a board; the third system does not Electrical and plumbing can be checked against a state roster before anybody starts; heating and cooling cannot.
- What the crew hands back is what the figure has to answer for A better roof and better cladding belong inside the amount insured, not in a note sitting beside it.
- Duration, occupancy, and the one input already decided Nobody sleeps in the building from one closing to the next, and the prior losses arrive already written.
- How much of the building comes apart, and what that answers to A finishes job and a job that opens the shell sit on different contracts, and the scope decides which.
Certified counters, the state route, and the buildings the statute leaves out
Montana adopts its construction codes at state level, and the published list reaches every trade on a gut rehab: building, residential, existing building, plumbing, mechanical, fuel gas, electrical and energy codes all sit on it. What is not centralized is the counter.
Certified city, county and town programs issue their own permits. Outside jurisdictions certified to issue their own, state law exempts several classes of building from the requirement to obtain a state building permit, and one class is residential: the Building Codes Bureau names residential buildings containing less than five dwelling units among them.
That clause inverts easily, so take it slowly. It exempts small residential buildings from the state permit, in territory outside certified jurisdictions. It is not a statement that no permit is ever needed, and it says nothing about what a certified city, county or town asks for. Where a certified program covers the address, that program is the office the job answers to.
Where the state route does apply, review comes before paper: construction plans go to the Bureau for approval, and the permit follows. The Bureau also attaches a consequence to starting early — buildings begun before a permit is obtained may be assessed an investigation fee and may subsequently require significant corrective construction. Both halves are calendar problems as much as compliance ones: plan review is time the project does not control, sitting at the front of the term rather than the end, and corrective work is scope that appears after the money is committed.
The peril moving this market, and the loss that was never inside the form
On the causes themselves this regulator is unusually plain. Fire damage is covered like any other covered peril, and the office puts hail, wind, explosion and theft in the same sentence, with the caveat that limitations and exclusions apply and that wear and tear is an exclusion rather than a covered cause of loss. On a tired building that second caveat is the one a rehab meets first.
Flood sits outside the placement entirely. The Commissioner’s office states that flood damage is generally not covered by an ordinary residential policy and points owners to the National Flood Insurance Program, and it notes that private flood insurance may be available and may be more affordable. Both routes are worth pricing.
Then there is the peril reshaping this market, which is wildfire. The Commissioner’s own article says that many owners, especially those near wildland-urban interfaces, are facing steep premium hikes or non-renewal notices. A notice landing mid-hold is a harder problem than a decline at the outset, because the building is half apart when it arrives and a replacement has to be found at peak exposure. Which is the strongest practical argument for using the disclosure right early rather than at renewal: whatever the score was built from is what the next market will be looking at too.
A program that turned into a license without turning into an examination
The contractor credential here is run by the Department of Labor & Industry, and it recently changed shape. The Department states that House Bill 239 moved the state from a basic registration framework to an official licensing program, with contractors holding an active registration converted across to the new license.
The word on the certificate is therefore newer than the substance standing behind it. The Department’s own program FAQ sets out an application fee, a business-entity registration step, and workers’ compensation and unemployment coverage for employees — and it sets out no examination and no trade-experience requirement. What the certificate proves is that a business was formed, filed and paid, and carries what the program demands for the people it hires. It is not evidence that anyone assessed the work.
Two clauses in the definition reach further than investors expect. The first is breadth: it covers anyone who offers to construct, alter, repair, add to, subtract from, improve, move, wreck or demolish a structure for another, and it names installing floor covering and installing or repairing roofing or siding specifically. The second reaches a flipper directly: it also reaches an owner doing that work on their own property where members of more than one trade are employed on a single job or under a single building permit. An investor running a framer and an electrician under one permit is inside that sentence, not outside it.
Engaging a person to perform work for which that person is not licensed is in turn defined as unprofessional conduct, which lands the consequence on whoever holds the agreement. That argues for interrogating a certificate of insurance rather than collecting one: a trade contractor buys general liability around the exposure that contractor creates, and an additional-insured line on their document is evidence of what they bought, not cover standing over the building in your name.
Two boards with a roster to search, and one trade with none
Electrical work is licensed by the Montana State Electrical Board, which issues Journeyman Electrician and Master Electrician licenses. Plumbing is licensed by the Montana Board of Plumbers, which issues Plumber Master and Plumber Journeyman licenses. Both boards sit under the same department that runs the contractor program.
The third mechanical trade has no state board at all. This state runs a board for wire and a board for pipe and none for heating and cooling — a finding rather than a gap in the research. There is no roster to search for the crew swapping out the furnace, because the state keeps none.
The result on a gut rehab is lopsided verification. Two of the three systems trades can be looked up against a state record before a dollar moves; the third is evidenced through the written agreement, the certificate and the permit instead. The contractor definition above does not narrow for the trade with no board behind it.
Real-World Scenario: The siding order is placed early, which is how most siding orders are placed — on price and lead time, with nobody from the insurance side in the room. The house sits outside any certified local program, so the permit question is answered by an exemption rather than at a counter. Months later a renewal quote arrives carrying a wildfire score, and the owner learns the scoring data can be requested. It can. But the cladding that might have argued with it is already on the wall and already paid for. Nothing there was done wrong — it was simply done in an order that left both Montana measures with nothing to work on.
The amount is argued to a roof nobody has bought yet
The limit on a renovation policy answers to a building that is still a schedule. That makes the figure a forecast, and forecasts get argued — against what the house cost, against what the work will cost, against how much of the structure the scope is actually replacing.
Montana puts a particular pressure on that forecast. If the exterior specification moves toward ignition-resistant roofing or fire-resistant siding, which is what the mitigation measure invites, the completed house contains products nobody costed when the figure was first assembled. Carrying that growth into the amount is the entire exercise. Shading the figure down to shade the premium down is the one saving on this page that cannot be repaired later: it is collected in installments and surrendered in a single afternoon.
Duration, occupancy, and the line that arrives already written
Two rows sit near the floor of the stack because they are settled before anybody writes a submission, not because they matter less.
The first is that nobody is living in the building and nobody is meant to. The unoccupied conditions written into an ordinary dwelling form assume a household, and a rehab has none from the moment the seller hands the keys across to the moment a buyer takes them — the quiet weeks after the last trade drives away very much included. In wildland-urban interface territory that stretch carries a second cost, because a hold long enough to cross a renewal date is a hold that has to survive one.
The second is the loss history. Everything above it is still movable at the point of binding. That row is not, and the only useful thing to do with a fixed row is account for it in the submission rather than let it turn up unannounced.
What the wrecking list decides about the placement
Only now does the question most cost guides open with arrive. If the job never goes past the surfaces — cabinets, flooring, paint, fixtures — the house stays a house throughout, and the placement is an endorsed dwelling policy with the cosmetic repair endorsement doing the work, which is the territory house flipping insurance covers. Open the framing, the roof deck or the service runs and the address is a construction site for the duration, and the cover has to follow it there.
The reason that question waits until the eighth row in Montana is the exterior specification. A refresh that grows a new roof and new cladding has changed what is being insured, and possibly which office is inspecting it, both after the quote was given. The demolition list settles that question, and on an exterior scope here the demolition list is not settled until the specification is.
Send the specification before the market is chosen
Lead with the address and the exterior scope in the same message, because between them they decide whether either wildfire measure is in play at all. After that: the written scope with the roofing and siding named; what the house cost and what the work will cost; the schedule, with the listing weeks counted in; whether a certified local program or the state route issues the permit; the names and coverages of everybody on site; and whatever is already on the loss record.
The Commissioner, the two boards, the split permit counter and the claims that actually turn up on rehabs here are laid out on the Montana fix and flip insurance page, with every state this agency can write in beside it. Once the job can be described properly, put it in front of us, or find out who reads it first.
This guide covers what drives the cost of a Montana rehab. The state page covers who licenses the trades, who issues the permit and how a project there is placed: fix and flip insurance in Montana.
The bottom line
Montana is the state where a renovation’s shopping list and its insurance file meet in the same week — one measure lets an owner request the data and methodology behind a wildfire risk score, and a companion measure lets an insurer offer a reduction for mitigation and resilient construction such as ignition-resistant roofing and fire-resistant siding, and both are live only while the roof and the cladding are still unbought. Which office issues the permit, what the contractor credential was actually checked against, and how long the building stands empty are all read after that.
Frequently asked questions
Our roofing and siding order goes in next week. Does the timing of that decision reach the insurance side at all?
It does, and the timing is most of it. The companion measure here lets an insurer offer a reduction for mitigation and resilient construction, and an insurer can only weigh what is specified or installed. Material already on the building is easier to evidence than material described as an intention, so the specification is worth settling before the placement is finalized rather than after the order has shipped.
The state exemption reads as though a small house needs no permit at all. Have I understood that correctly?
No, and this is the clause that inverts most often. Outside cities certified to issue their own permits, state law exempts small residential buildings from the need to obtain a state building permit. That is an exemption from the state permit, in areas outside certified jurisdictions. It says nothing about what a certified city, county or town requires, and those programs issue their own permits.
Engaging somebody for work they are not licensed for is called unprofessional conduct. Whose exposure is that on my job?
The person who did the engaging. The Department defines engaging a person to perform work for which that person is not licensed as unprofessional conduct, which places the consequence on the party holding the agreement rather than on the crew that showed up. On an owner-coordinated rehab, that party is frequently the investor, which is why the credential check belongs before the start date.
There is no state board standing behind the heating work. Does an underwriter read that trade differently?
Not differently, but with less to read. The state runs a board for electrical work and a board for plumbing, and it runs none for heating and cooling, so two of the three systems trades can be verified from a state roster before anybody starts and the third cannot. What replaces the roster is ordinary evidence: the written agreement, the certificate of insurance, and the permit record.
We are told the limit answers to the finished house. Which finished house — the one in the original plan, or the one with the upgraded exterior?
The one the crew actually hands back. If the exterior specification moved toward ignition-resistant roofing or fire-resistant siding partway through, the building at the end of the schedule contains materials that were not in the figure when it was first argued. That change belongs inside the amount insured rather than beside it, and it is a mid-term conversation, not a renewal one.
A non-renewal notice arrived while our Montana rehab was still open. How is that different from the house simply standing empty?
An empty house is priced at the start; a notice arriving mid-hold has to be answered while the building is at its most exposed. The Commissioner’s office has said that owners near wildland-urban interfaces are facing steep premium hikes or non-renewal notices, which makes a long hold a hold with a renewal inside it. Say so at submission rather than discovering it at the renewal date.
About the author

Nate Jones, CPCU, is the founder of Wexford Insurance and Fix and Flip Guard Insurance, a specialty agency placing fix-and-flip real estate investment coverage in 48 states across 10+ carrier markets. The Montana projects he takes on are the ones where the roofing and siding decision is still open, because that is the window in which a wildfire score and a premium reduction are both still arguable — and the point after which neither of them is. Reach him through the Fix and Flip Guard Insurance quote form or call 888-346-2414.