
What Happens When a Rehab Runs Past the Policy Term?
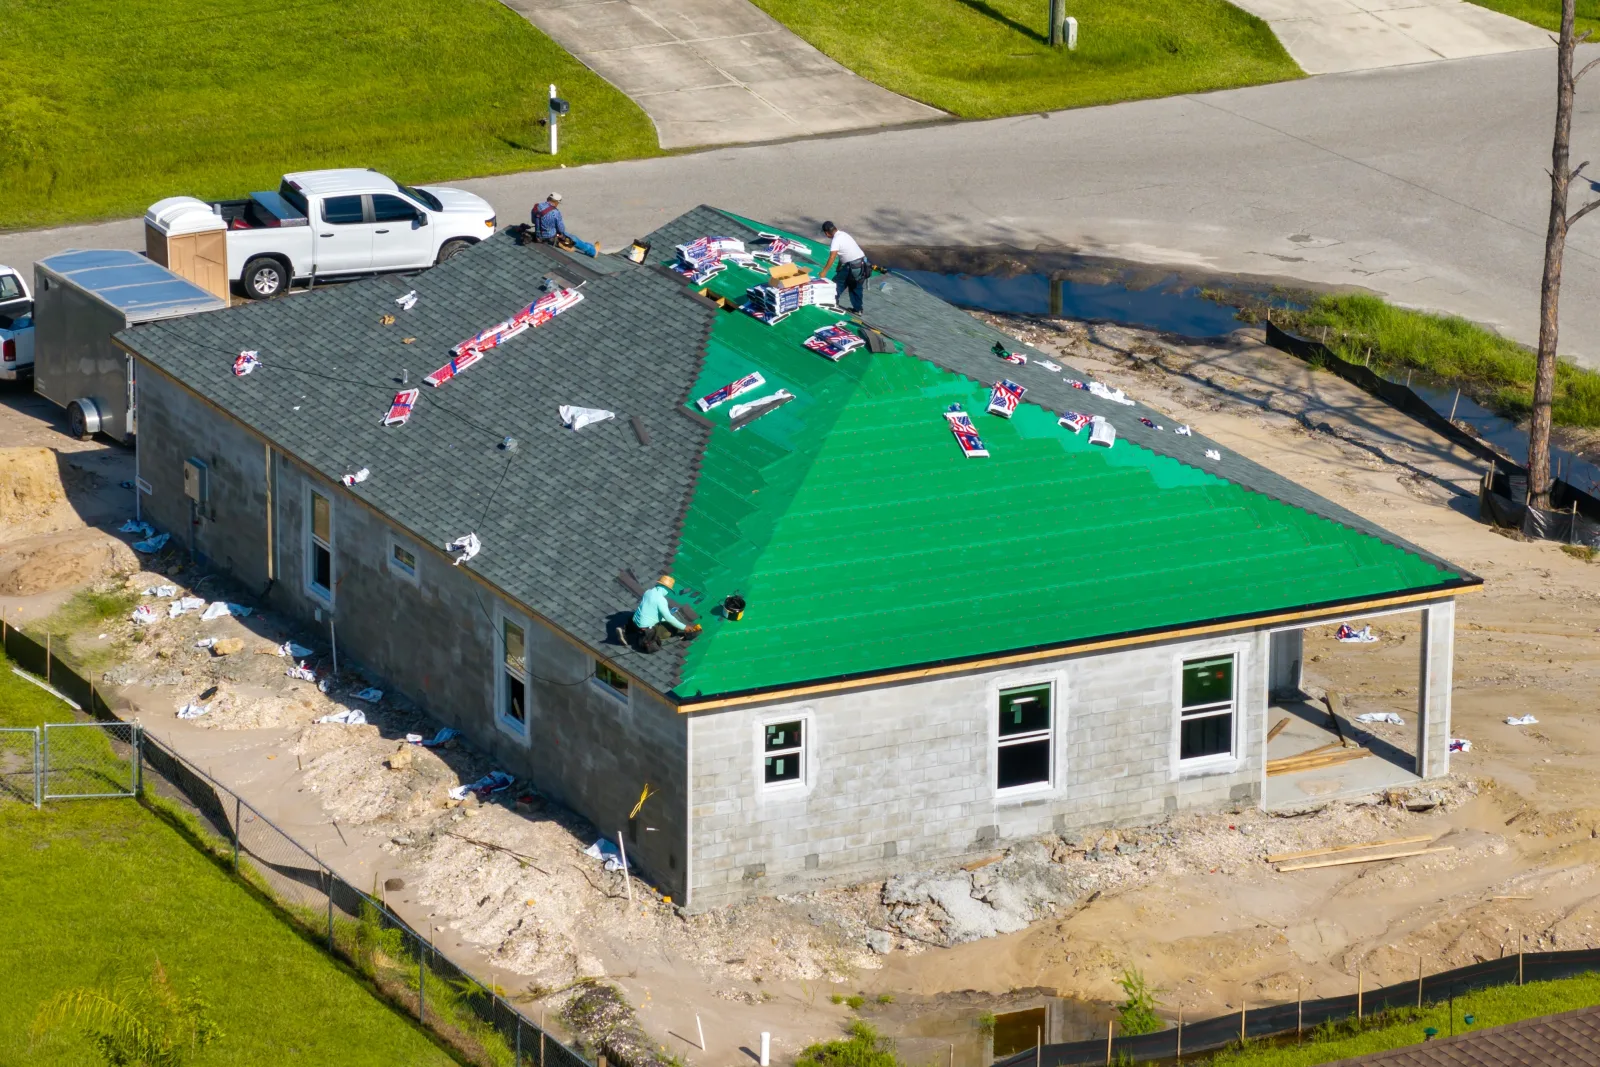
When a rehab runs past the end of the policy, the policy does not stretch to fit the schedule. The NAIC glossary defines a policy period as the time during which coverage is in effect, and a loss after that time belongs to nobody but you. What follows is a set of decisions, and they are easier made while the term still has room. This post lays them out as a calendar: what to ask while time remains, what an extension request needs, what happens to the lender’s requirements, and how extending differs from replacing.
The end date is printed on the declarations page, and the schedule is only a forecast
Begin with the document that fixes the date. The New York Department of Financial Services page on basic coverage lists the policy period among the items a declarations page shows, beside the policy number, the insured address, the coverage types and limits, the deductible and the premium. That one line is the edge of your cover, and it was set on the day you bought the policy.
The schedule you gave the agent that day was a forecast. Forecasts on a rehab move for reasons that have nothing to do with the policy: an inspector who cannot come until later, a supplier who ships late, a drawing revised after the plan reviewer asked a question. Holding costs on a flip are billed against days that pass, and the premium belongs on that list because it was bought for a span of days that now looks too short.
So the first decision is not about coverage at all. It is noticing, early and in writing, that the finish date and the end date are no longer the same date, and starting the calendar from there.
While the term still has room, ask what each path would require
Weeks before the end date, the questions you can ask are cheap and the answers can still change what you do. Ask them in writing, and ask the agent to name the document each answer comes from.
- Can this policy be extended, or is the only route a new policy written for a later period?
- If it can be extended, what does the underwriter want to see, and by what date does the request have to arrive?
- Does an extension keep the same form, the same limit and the same settlement basis, or does it reopen them?
- Do any completion or occupancy triggers in the form end cover before the new end date, whatever the calendar says?
- What does the policy ask of me if work stops for a stretch and nobody is at the house?
The last two are where a late project is most likely to be surprised. The post on occupancy and completion triggers lays out how those clauses are built, and this post does not repeat it. The only point to carry over is that a printed end date is a ceiling, not a promise that cover lasts until it arrives.
An extension request is only as good as the permit file and the schedule behind it
An underwriter asked to carry a house for more time is being asked to believe a new forecast. What persuades is paper, so assemble it before you ask.
Start with the permit file. The status of each permit, the inspections that have passed and the ones still waiting are the clearest evidence of how far along the work is and what stands between the house and completion. The post on permits and inspections on a rehab timeline explains why those dates sit with the jurisdiction and not with the crew, which is the reason a revised schedule should name them.
Add the revised schedule itself, with the reason for each change stated plainly. If the scope of work has grown, say so, because a limit written for the original scope may no longer describe the house. If the draw schedule has moved, include it, since it shows when money arrives and therefore when work can resume. Photographs of the present stage of the work, dated, belong in the packet as well.
Last, say what has not changed: the same crew, the same address, the same plan to sell. A request that lists what moved and what stayed put is easier to answer than one that leaves the reader to work it out.
A builders risk term is written in words, and California describes what follows completion
The California Department of Insurance commercial guide describes builder’s risk as added to a policy for a one-year minimum term, to cover a new structure or an existing one undergoing additions, alterations or repairs. It says cancellation on completion is allowed pro rata, while a mid-term cancellation brings a short-rate penalty. It also describes a reporting or renovations form, which lets the amount carried follow the stage of completion.
Read those three statements as questions for your own builders risk placement, not as terms of it. If your form is written for a minimum span, what does the end date mean for a project that finishes early, and what does it mean for one that finishes late? If it follows the stage of completion, who reports that stage, on what rhythm, and what happens to the limit when the report says the work is further along than the schedule predicted?
Notice the direction of the penalty. The California guide ties the short-rate penalty to cancelling mid-term, so the tidy-looking move on a calendar, ending the policy early and starting a fresh one, is the move to ask about before making.
On the dwelling path, the same date arrives with a different set of questions
A finish-work job sits on the dwelling path, a dwelling policy with a cosmetic repair endorsement, and the paper reads differently. The North Carolina Department of Insurance page calls this a dwelling fire policy, says it can cover much more than fire, and describes it as used for someone who does not make the property a primary residence. It lists the basic, broad and special forms, notes that the basic form names its perils and settles claims on actual cash value, and says replacement cost is sometimes optional. It also lists vacant homes among those a dwelling fire policy may suit.
For a late project the useful reading is a comparison. When the term ends and you renew or rewrite, does the form stay the same, and does the settlement basis? The dwelling policy with a cosmetic repair endorsement page sets out what that endorsement is meant to cover, and the answer to whether a late job still fits it depends on whether the work is still the finish work the endorsement describes.
If the job has drifted toward structural work during the delay, say so before you ask for an extension. The post on a short-horizon dwelling policy covers what that kind of term is built for, and it is the right place to check whether a term shorter than the project was ever the right fit.
Real-World Scenario: A flipper bought a worn house with a gut rehab scope and a policy period that matched the original schedule. A permit revision and a delayed inspection push the finish date past the end of the policy period. The flipper calls the agent while the term still has room and sends the revised schedule, the permit status and dated photographs of the work done so far. The agent explains that the underwriter wants the new expected completion date and the stage the work has reached. The loan documents call for proof of continued coverage, so the flipper asks for the new declarations page to be sent to the lender directly. When the original period ends the house is still unfinished, and the file already shows what continues.
The lender’s requirements do not pause when the policy period ends
Whatever you decide about the policy, the loan documents keep their own calendar. Read them for what they say about proof of coverage, about notice and about who must be named, and put the dates side by side with the policy period.
The Wisconsin insurance regulator’s consumer guide offers one described consequence of letting cover lapse, on an owner-occupied mortgage. It says that if coverage lapses the lender buys coverage to protect its own interest and the borrower pays for it, known as lender-placed insurance. That is a statement about that kind of loan and that guide. It is not a statement about hard money lenders, and this post does not claim your lender would do the same.
What the example does support is the questions. Does your loan document set a date by which new proof of coverage must arrive? Does it say what the lender may do if the old policy ends and nothing replaces it? Does an extended or replaced policy keep the lender’s name in the same place and spelling? The post on how rehab financing routes differ is a good place to look at what a lender asks for that is not about money.
Extending the policy and replacing it are different transactions
An extension continues the placement you have. A replacement ends one placement and starts another, and the paper should say which one you chose.
Ask whether a replacement carries over anything from the old policy, such as a continuous effective date, or whether the new cover begins on a fresh date with its own conditions. Ask whether the stage of the work is disclosed on the new application, since a house midway through a rehab is a different submission from a house about to start one. The post on when cover attaches on a rehab explains why the start date of any placement is a document question, and that holds for a replacement as much as for the original.
Ask about the limit. The amount that suited the house at the start may not suit it now, and the coinsurance condition and the moving limit is worth reading before you accept a renewed figure. Finally, ask what happens to the old policy: whether it ends on its date, whether it is cancelled early, and what the cancellation terms say about any refund or penalty.
What a late schedule puts at risk
What a late schedule puts at risk on the policy, laid out as rows from continuity of cover through completion triggers, lender proof, the amount carried and the cancellation terms.
- Continuity of cover A gap between the old period and a replacement leaves the work unprotected on those days
- Completion and occupancy triggers A trigger can end cover before the printed date, so read the clause against the schedule
- The lender’s proof of coverage Loan documents may call for current proof, so read them before the date arrives
- The amount carried A limit set for the original scope may not describe the house at its present stage
- Form and settlement basis A renewal can change the form or the valuation, so compare the old and the new documents line by line
- Cancellation terms on the old placement Early cancellation can carry a penalty on some forms, so ask before ending a policy
A calendar to run backward from the date on the declarations page
Put the end date on a calendar and work backward. This is a list of decisions, not a set of deadlines for any particular policy.
- Many weeks out: compare the finish date to the end date, and ask the agent what extending requires.
- Weeks out: assemble the permit file, the revised schedule, the scope of work and dated photographs.
- Weeks out, in parallel: read the loan documents for proof-of-coverage dates, and ask your lender in writing what it needs.
- Days out: decide between extending and replacing, and get the answer on the amount carried, the form and the cancellation terms in writing.
- On the last day: confirm the new declarations page exists, shows the right period and carries the lender’s name.
The time that matters most is the earliest, because it is the only time every option is still open. A project that is late is not unusual; the soft costs that accumulate during a delay are a reminder of how much of a rehab sits outside what a property policy pays. What you control is whether the paper keeps up with the work. If you are weighing a structural job, the fix and flip insurance overview describes how the two policy paths are set out, and a licensed agent can walk through your own dates. For a finish-work project the dwelling-policy path is described under house flipping insurance, and your dates and scope are the place to start.
The bottom line
The policy does not move when the schedule does, so the decisions fall on the calendar before the printed end date: what to ask, what to send, what the lender needs and whether you are extending or replacing. Each is easier while the term still has room.
Frequently asked questions
Does cover stop on the date printed on the policy?
The NAIC glossary defines the policy period as the time during which coverage is in effect, and the declarations page prints it. Other clauses can end cover earlier than the printed date, so ask the agent to read the end date and the completion and occupancy wording together.
Can I simply buy a new policy the day the old one ends?
That is replacing, not extending, and it is a new transaction with its own application. Ask the agent what the new underwriter will want to know about the stage of the work, and whether any day falls between the old period and the new one without cover.
If the lender buys its own coverage after a lapse, who pays for it?
A Wisconsin consumer guide describes this for a mortgage on an owner-occupied house: the lender buys coverage to protect its own interest and the borrower pays for it, which the guide calls lender-placed insurance. It does not speak for hard money lenders or any other loan. Read your own loan documents and ask your lender in writing.
Do I get anything back if the work finishes ahead of the policy period?
The California Department of Insurance describes builder’s risk cancellation on completion as allowed pro rata, and it describes a mid-term cancellation as carrying a short-rate penalty. Whether your form follows that pattern is a question for your policy. Ask before you cancel anything.
The crew stopped for a stretch and nobody is at the house. Is that a problem for the policy?
It can be, and the answer sits in the vacancy and occupancy wording of your own form. The North Carolina page lists vacant homes among those a dwelling fire policy may suit, but that speaks to fit and not to conditions during a pause. Tell the agent about the pause and ask what the policy asks of you meanwhile.
Does an extension change how much the policy will pay?
It can. The California guide describes a reporting or renovations form that lets the amount carried follow the stage of completion, so the figure on an extended policy may move with the work. Ask the agent to show you the limit before and after the request, and which stage of completion each figure assumes.
About the author

Nate Jones, CPCU, is the founder of Wexford Insurance and Fix and Flip Guard Insurance, a specialty agency placing fix-and-flip real estate investment coverage in 48 states across 10+ carrier markets. Nate reads the permit file and the revised schedule next to the policy period, because a late rehab is a question about dates before it is a question about coverage. Reach him through the Fix and Flip Guard Insurance quote form or call 888-346-2414.